Author: Andy Mohr Hyundai Team
Deciding how to pay for a new Hyundai matters just as much as choosing the right model for downtown errands or weekend trips to Lake Monroe. Whether you lease an Elantra for a quick 18-minute commute or finance a Tucson to explore Hoosier National Forest long-term, evaluating your payment options helps balance everyday living costs. Andy Mohr Hyundai has maintained a long-standing presence in the community, acting as a reliable, long-term automotive partner for drivers in Bloomington and nearby areas like Columbus, Greenwood, Bedford, and Terre Haute. With deep local knowledge and trusted experience, our team brings proven expertise to servicing and maintaining Hyundai vehicles, ensuring they safely handle our distinct Midwestern seasons.
Key Takeaways (TL; DR)
Understanding your auto financing options boils down to knowing how your credit profile, lease versus buy preferences, and budget align with your daily driving needs. For Bloomington residents—whether you're commuting to the Indiana University campus or taking weekend trips down State Road 37—getting a clear picture of these core financing elements ensures you secure a payment plan that comfortably fits your lifestyle.
- Credit History Matters: Your credit score directly influences your interest rates and loan terms. Securing a lower rate means paying less overall, making a spacious three-row model like the 2027 Hyundai Palisade more accessible for your family's budget.
- Hyundai Motor Finance Benefits: Applying directly through Hyundai's official lending arm unlocks access to competitive rates and manufacturer-exclusive promotional offers. You can often secure pre-approval before even taking a test drive.
- Buying Versus Leasing: Financing a vehicle builds long-term equity, which is ideal if you plan to keep the car for several years. Alternatively, leasing acts more like a multi-year agreement—typically lasting 24 to 36 months—resulting in lower monthly payments and the flexibility to upgrade sooner for those frequent outdoor trips to Lake Monroe.
- Flexible Lease Returns: When your contract concludes, you aren't locked into a single path. You can purchase your current vehicle at its pre-determined residual value, lease a brand-new model, or simply hand over the keys and walk away.
- Targeted Incentive Programs: Hyundai provides specialized rebates that can reduce your bottom line. Recent college graduates stepping into the workforce or military personnel can often apply these exclusive cash offers directly toward their down payment.
- Pre-Purchase Preparation: Before finalizing any paperwork, gather your essential documents, review your credit report, and establish a firm monthly budget. This proactive approach saves time when you are ready to finalize your financing on a highly efficient commuter like the 2026 Hyundai Elantra.
How Hyundai Auto Financing Works
When you choose to finance a vehicle like the Hyundai Tucson, you are taking out an auto loan to cover the purchase price, usually through a lender like Hyundai Motor Finance or a local Indiana credit union. You then pay off that balance—plus an agreed-upon interest rate—in predictable monthly installments over a set period, known as the loan term. Typical terms run anywhere from 48 to 72 months, depending on your preferred payment size. What this means for Bloomington drivers is straightforward: rather than paying the full cost upfront, you spread the expense into manageable chunks while immediately taking your new Hyundai out on State Road 37 for your daily commute.
Every monthly payment you make builds equity, meaning you own an increasing percentage of the vehicle's true value. Once you finish that final installment, the lender hands over the official title, making the car entirely yours. Unlike a lease where you eventually return the keys, financing comes with zero mileage limits. That gives you the ultimate freedom to rack up miles on weekend trips down to Lake Monroe or pack the cargo area with gear for tailgating near the Indiana University campus without worrying about overage fees. You can customize your ride, drive as far as you want, and eventually sell or trade the vehicle on your own schedule.
Navigating Your Loan or Lease With Hyundai Motor Finance

Securing the right payment plan doesn't have to be a stressful hurdle. Hyundai Motor Finance serves as the automaker’s official lending arm, designed to streamline the buying process from start to finish. What this means for Bloomington drivers is fewer headaches coordinating with third-party banks and more time enjoying weekend escapes down State Road 37. Instead of shopping around for hours, you gain direct access to factory-backed lending options in one seamless step.
Whether you're eyeing a flexible 36-month lease on a 2026 Tucson or considering a traditional auto loan for a sleek IONIQ 6 to handle daily commutes to the Indiana University campus, getting started is simple. You can easily initiate online pre-approval before even leaving your house. This gives you a clear picture of your purchasing power ahead of time, letting you focus entirely on picking the perfect trim and features rather than crunching numbers on the showroom floor.
When reviewing your application, the finance team looks at your income and overall credit history to build a customized payment structure. Keep in mind that available offers vary by credit, but well-qualified buyers frequently unlock exclusive benefits unavailable through standard lenders. That might include factory-direct promotional APRs, targeted lease cash incentives, or loyalty bonuses for returning drivers, keeping modern innovation well within reach.
How Does Leasing a Hyundai Actually Work?
Choosing to lease a new Hyundai functions like an extended, structured rental agreement rather than an outright purchase. Instead of financing the full sticker price of the car, your monthly payment is calculated based on the vehicle's anticipated depreciation during a set timeframe—typically 24 to 36 months. This difference between the car's initial cost and its projected end-of-term worth is known as the residual value. Alongside this depreciation portion, lease payments also include standard taxes, fees, and a rent charge referred to as the money factor. For example, if a 2026 Hyundai Tucson depreciates by a projected $10,000 over a three-year lease, your base monthly payments are designed to cover just that $10,000 spread out over 36 months, rather than the SUV's entire purchase price.
Because you only pay for the portion of the car's lifespan that you use, leasing generally yields lower monthly obligations than traditional auto financing. For drivers commuting down State Road 37 or running daily errands near the Indiana University campus, this structure offers highly predictable transportation costs. That matters for local households because it allows you to consistently drive a late-model vehicle equipped with modern safety features and active factory warranty coverage, all while giving you the flexibility to seamlessly transition into a brand-new Hyundai once your contract concludes.
What Happens When Your Hyundai Lease Matures?
As your lease term wraps up, you generally have three primary paths: buying your current car, trading it for a new one, or simply handing the keys back. For drivers around Bloomington, deciding what to do next often depends on how your daily habits have evolved. That means if you spent the last few years racking up miles on weekend runs down State Road 37, buying out the lease might save you from mileage penalties; if you kept your driving limited to the Indiana University campus, you might have plenty of equity to roll into a new ride. If you leased a Hyundai Elantra three years ago, purchasing it at its original residual value might actually cost less than financing a comparable used car today. Here is a closer look at your end-of-lease choices.
- Purchase Your Current Hyundai: If you want to keep the car you already know and trust, you can buy it outright based on the residual value established in your original contract. This bypasses any end-of-lease inspections and eliminates fees for excess wear or mileage.
- Upgrade to a New Lease or Finance Agreement: Vehicle technology moves fast. You can turn in your current ride and start a fresh agreement on a newer model. For example, you might swap an older gas-powered SUV for a 2026 Hyundai Tucson Hybrid to maximize fuel efficiency during stop-and-go traffic near College Mall.
- Return Your Vehicle and Walk Away: You are always free to close out the contract and return the vehicle. You will just need to schedule a complimentary pre-return inspection a few weeks before your turn-in date to evaluate tire tread, assess any dents, and check your final odometer reading.
Comparing Your Options: Financing vs. Leasing a Hyundai

The core difference is ownership: financing a Hyundai Tucson Hybrid over a typical 60-month term builds equity, while leasing covers only the depreciation for a set period. If you commute heavily down State Road 37 to Bedford, buying avoids mileage limits. Conversely, short trips to College Mall make a 10,000-mile-per-year lease ideal.
| Feature | Financing a Hyundai | Leasing a Hyundai |
|---|---|---|
| Ownership | You gain full ownership once the loan is completely paid off. | The lender retains ownership of the vehicle throughout the contract. |
| Monthly Payments | Generally higher, as your payments go toward the entire cost of the vehicle. | Often lower, because you only pay for the car's depreciation during the lease term. |
| Upfront Costs | Lenders usually recommend a down payment to reduce the total financed amount. | Standard drive-off costs typically include the first month's payment and acquisition fees. |
| Customization | You can modify, paint, or upgrade the car however you see fit. | The vehicle must remain in its factory condition without permanent alterations. |
| Mileage | Drive as much as you want without any contractual penalty. | Contracts include annual mileage limits (e.g., 10,000 miles), with per-mile fees for overages. |
| Wear & Tear | Dents or interior damage simply impact the car's future resale value. | You are responsible for penalty fees for any damage beyond normal daily use. |
| End of Term | Keep driving payment-free, sell the car privately, or trade it in. | Return the vehicle, purchase it at a pre-set residual value, or start a new lease. |
What Shapes Your Hyundai Lease or Loan Terms?
When you apply for a loan or lease on a new Hyundai, your final rate isn't pulled out of thin air. Lenders analyze a combination of your financial profile and the specific vehicle you want to drive. For Bloomington drivers balancing a daily commute down State Road 37 with weekend family outings to Bryan Park, securing favorable terms means freeing up more of your monthly budget. Here is exactly what banks evaluate to structure your custom offer.
- Your credit history: A strong credit score acts as the foundation for the lowest available Annual Percentage Rates (APR), signaling to lenders that you have a consistent track record of managing debt.
- Initial down payment: Putting more cash down upfront directly shrinks the principal balance. For example, adding just $1,000 to your down payment can lower both your monthly obligation and the total interest paid over the life of the contract.
- The financing timeline: Stretching a contract out to 72 months rather than 48 months lowers your immediate monthly payment, but you'll accumulate more interest overall.
- Vehicle selection: The exact model you choose plays a big role. Financing a brand-new 2026 Hyundai Tucson Gas, for instance, often unlocks manufacturer-subsidized promotions or special lease rates that aren't typically available for older used vehicles.
- Debt-to-Income (DTI) ratio: Lenders compare your gross monthly income against existing obligations, such as housing or student loans. A manageable DTI proves you can comfortably handle a new car payment while navigating living costs around the Indiana University campus.
Are There Unique Hyundai Discount Programs Available?
Yes, Hyundai provides several specialized rebate programs designed to lower the overall cost of a new lease or purchase. If you meet the criteria, you can typically apply a fixed rebate amount directly toward your down payment. Qualifying usually requires specific documentation, such as a recent university diploma or an active military ID. What this means for drivers around Bloomington is a more affordable path to reliable transportation, whether you are a newly hired faculty member commuting to the Indiana University campus or a local family running errands near College Mall. You can explore the brand's global vision and initiatives at Hyundai Worldwide, while taking advantage of these practical savings at the local level.
- Hyundai College Graduate Program: If you have recently earned your degree (typically within the last two years or graduating in the next six months) and have proof of employment, you can claim a rebate on a new model like the fuel-efficient Elantra. It is a helpful financial boost for young professionals transitioning from late nights near Showers Common into their first full-time careers.
- Hyundai Military Program: Active duty, veteran, and retired U.S. military personnel—as well as their spouses—can qualify for this targeted rebate. Requiring just a current Leave and Earnings Statement (LES) or honorable discharge paperwork, this offer makes upgrading to a spacious Tucson or Santa Fe a little easier.
- Owner Loyalty Offers: Current Hyundai drivers often unlock exclusive savings when purchasing a newer model or adding a second vehicle to the household. For example, if you trade in an older Sonata for a new Sonata Hybrid, you might trigger a loyalty bonus that stacks seamlessly on top of standard dealership discounts.
- Regional and Seasonal Promotions: Manufacturer incentives rotate frequently based on the season and Midwest inventory levels. Whether it is a winter lease special suited for navigating icy Bedford roads or a summer finance rate on a Palisade, these localized offers help maximize your purchasing power throughout the year.
Steps to Secure Your Hyundai Lease or Auto Loan

Securing the keys to a fuel-efficient Hyundai Tucson or an all-electric IONIQ 5 doesn't have to be a stressful ordeal. By kicking off the financing process online before you even merge onto State Road 37, you can dramatically streamline your visit. What this means for Bloomington drivers is less time sitting at a desk filling out paperwork and more time enjoying weekend getaways down at Lake Monroe. Here is the straightforward path to taking your new vehicle home:
- Request Pre-Qualification: You can view your likely financing terms through a soft credit check, which gives you a clear baseline budget without dinging your current credit score.
- Gather Your Documents: Before driving over from the Indiana University campus area, collect your valid driver's license, current auto insurance card, proof of income (such as your two most recent pay stubs), and a recent utility bill to verify your residence.
- Submit the Official Application: Once you pinpoint your exact model and desired terms, you will submit a full credit application. This step requires a standard hard credit inquiry from lenders to lock in your official, finalized offers.
- Review and Sign: Look over the final contract to confirm your Annual Percentage Rate (APR), term length, exact monthly payment, and any additional coverages—such as the optional Hyundai Protection Plan Vehicle Service Contract—before officially signing on the dotted line.
Paying Upfront vs. Spreading the Cost Over Time
Paying for a vehicle outright delivers the immediate satisfaction of full ownership without any monthly interest charges. For instance, if you decide to purchase a new 2026 Hyundai Tucson Hybrid in cash, you bypass monthly loan statements completely, freeing up your future income. What this means for Bloomington drivers is achieving long-term financial simplicity—a major plus whether you are an established professional near the Indiana University campus or simply someone who wants one less bill to manage. However, handing over a large lump sum depletes your liquid savings, meaning you have fewer funds readily available if an unexpected expense pops up.
On the flip side, financing lets you keep your cash reserves intact while breaking the vehicle’s price into smaller, predictable chunks. If you commute daily down State Road 37, taking out a standard 60-month auto loan allows you to drive home in a reliable, modern vehicle today while paying for it as you earn. Ever wonder why so many buyers choose this route? It is primarily because an auto loan preserves your emergency fund and leaves room in your budget for other life priorities. Ultimately, the best choice depends entirely on your personal comfort with monthly payments versus your desire to hold onto your current bank balance.
What Are the Pros and Cons of Each Payment Method?
Choosing between buying and leasing comes down to how you plan to use the vehicle and your financial timeline. For Bloomington drivers, this means balancing the appeal of lower monthly payments against the long-term value of ownership. Here is a clear breakdown of the benefits and tradeoffs to help you make a confident decision.
Pros of Financing a Hyundai
- Total Ownership: Once the loan is paid off, the vehicle is entirely yours to keep, sell, or trade in for an upgrade.
- Unlimited Mileage: Take spontaneous weekend trips down to Hoosier National Forest or commute daily to Columbus without ever stressing about odometer limits.
- Freedom to Customize: Want to add a permanent roof rack for hauling kayaks to Lake Monroe? When you finance, you can modify the car however you see fit.
- Long-Term Value: Buying allows you to fully maximize Hyundai’s legendary 10-year/100,000-mile Powertrain Limited Warranty well after your standard loan term ends.
Cons of Financing a Hyundai
- Higher Upfront and Monthly Costs: Purchasing a new Tucson typically requires a larger down payment and higher monthly installments than leasing the exact same trim.
- Post-Warranty Upkeep: After the 5-year/60,000-mile New Vehicle Limited Warranty expires, you become fully responsible for the cost of major repairs.
- Natural Depreciation: As with any major purchase, the resale value of your vehicle will naturally decline as it ages and gains mileage.
Pros of Leasing a Hyundai
- Budget-Friendly Payments: Because you only pay for the vehicle’s expected depreciation during a standard 36-month term, your monthly out-of-pocket costs are generally much lower.
- Consistent Tech Upgrades: Leasing makes it easy to step into a new model like the IONIQ 5 every few years, giving you access to the latest EV range advancements and smart safety innovations.
- Built-In Warranty Protection: A typical three-year lease perfectly aligns with the new-vehicle warranty, meaning you are covered for virtually all mechanical defects while you drive it.
- Hassle-Free Returns: At the end of the contract, you simply hand the keys back to the dealership—no need to negotiate a trade-in price or find a private buyer.
Cons of Leasing a Hyundai
- Zero Equity: Because you are essentially renting the vehicle, you won't have a trade-in asset to put toward your next car.
- Mileage Caps: Most leases restrict you to 10,000 or 12,000 miles annually. If your daily commute from Bedford up State Road 37 pushes you over that limit, per-mile penalty fees quickly accumulate.
- Condition Requirements: You are on the hook for excess wear and tear. Minor dents or bumper scrapes from tight parking spots near the Indiana University campus could cost you out of pocket at turn-in.
- Strict Factory Condition: You must return the vehicle exactly as you received it, meaning permanent aftermarket modifications are not allowed.
Smart Strategies for Maximizing Your Vehicle Investment
Securing a great value on a new vehicle—whether you have your eye on a 2026 Hyundai Tucson Gas SEL or a highly efficient Elantra Hybrid Blue—takes a bit of strategy before you ever step onto the lot. What this means for Bloomington drivers is that knowing exactly what to negotiate and when to shop can noticeably reduce your total cost of ownership. Keeping your monthly payments low leaves more room in the budget for weekend outings to Lake Monroe or dining around Fountain Square Mall. By understanding the core mechanics of auto financing and pricing, you stay in total control of the transaction.
- Review Your Credit Early: Pull your credit profile well before you actually need a car. Correcting a small reporting error can bump your score up a tier, and a 1% drop in your Annual Percentage Rate (APR) over a standard 60-month loan can save you hundreds of dollars in interest.
- Gather Multiple Financing Quotes: Do not rely on a single source to fund your loan. Get pre-approved by a local credit union or bank first, then see if the dealership can beat those terms. You can use resources like Edmunds to research current average financing trends.
- Time Your Purchase Wisely: The end of the month, financial quarter, or calendar year often aligns with manufacturer sales goals, which can translate into better consumer incentives. Late summer and early fall are also prime times, as lots begin making room for incoming model years.
- Focus on the Out-the-Door Price First: It is easy to get distracted by appealing monthly payment targets, but always finalize the total vehicle price before discussing leases or loans. Treating the vehicle's cost and your financing strategy as two distinct conversations keeps the math entirely transparent.
- Master the Vocabulary: If you are leasing a Hyundai, familiarize yourself with terms like "capitalized cost" (the negotiated price of the vehicle) and "money factor" (the interest rate). If you are buying, focus strictly on the APR, the exact length of the loan term, and the total amount financed after your down payment.
- Separate Your Trade-In: Obtain an independent valuation for your current vehicle from trusted authorities like Kelley Blue Book before negotiating. Treating your trade-in as a secondary, separate transaction ensures you receive fair market value without complicating the purchase of your new car.
Frequently Asked Questions (FAQs)
What should I look for in my financing paperwork?
Rooted in our commitment to transparency and convenience, Andy Mohr Hyundai's finance professionals will review your entire agreement with you, ensuring you fully understand the terms, interest rate, and total financed amount. Our team takes the time to explain every detail alongside you, so families heading to College Mall or eco-conscious students commuting to the Indiana University campus feel completely confident in their purchase.
How does Andy Mohr Hyundai ensure you only receive the financing options you want?
Dedicated to an exceptional car-buying experience, the finance staff at Andy Mohr Hyundai carefully explains each optional protection plan without pressure, so you remain fully in control. Our team customizes your coverage to match your specific driving needs, whether you take weekend trips to Lake Monroe in a Tucson or navigate the downtown Courthouse Square in an Elantra.
How does Andy Mohr Hyundai ensure transparent pricing with no hidden financing fees?
By providing strict no-haggle pricing, Andy Mohr Hyundai’s finance team clearly outlines every line item on your contract to guarantee absolute transparency. We break down the exact costs before you sign, providing affordable ownership that perfectly aligns with cost-conscious households across the Bloomington community.
How does the Andy Mohr Hyundai finance team work with you to select appropriate coverage options?
To ensure your peace of mind, our staff collaborates directly with you to identify which service options fit your budget and daily driving routine. From safeguarding an IONIQ 5 for short eco-friendly commutes to protecting a spacious Palisade for regular trips down State Road 37, Andy Mohr Hyundai guides you to the right choices for your lifestyle.
How does the Mohr to Your Door program at Andy Mohr Hyundai make buying a car more convenient?
Andy Mohr Hyundai offers the Mohr to Your Door program to deliver your new vehicle for free within 150 miles of our dealership. This service allows you to finalize your paperwork through our virtual showrooms and receive your Hyundai right in your driveway, saving you a trip across town.
How does Andy Mohr Hyundai support the local community alongside its dealership services?
Beyond providing reliable transportation, Andy Mohr Hyundai proudly serves as a corporate sponsor for New Hope for Families. We are deeply passionate about giving back to the local community, blending our family-owned values with active support for Indiana residents and local organizations.
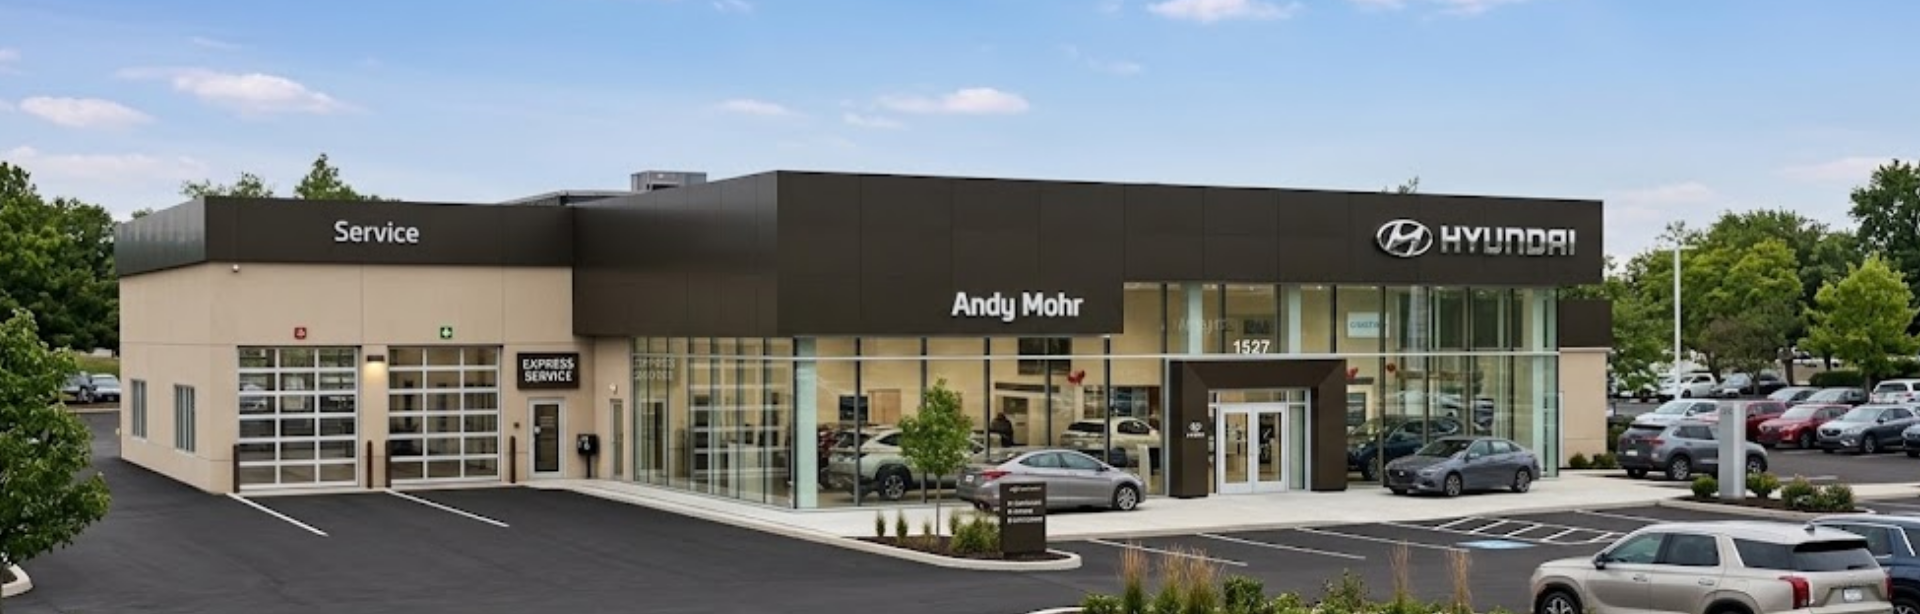
About Andy Mohr Hyundai
At Andy Mohr Hyundai, a proud member of the Andy Mohr Automotive Group since 2016, we are dedicated to providing an exceptional car-buying experience rooted in our family-owned values and commitment to the Indiana community. We believe in transparency and convenience, offering no-haggle pricing, virtual showrooms, and the Mohr to Your Door program, which delivers vehicles free within 150 miles. Our service team, featuring Hyundai-trained technicians, ensures your peace of mind with complimentary car washes and secure service options, all while you enjoy the comforts of our eco-friendly facility. As a Carfax Top Rated Dealer and a corporate sponsor for New Hope for Families, we are passionate about serving both our loyal customers and our local community, offering exclusive events, generous military incentives, and a range of first-time buyer programs. Come experience the difference at Andy Mohr Hyundai, where your satisfaction drives everything we do.